Our Latest Discussions
Medigap Plan G vs Plan N: Best Choice for Florida
Medicare, Medigap, Plan G, Plan N, Florida, Treasure Coast
Medigap Plan G vs. Plan N: Which Medicare Supplement Is Best for You?
If you live on the Treasure Coast or anywhere in Florida and are trying to choose between Medigap Plan G and Plan N, you’re not alone. These are two of the most popular Medicare Supplement options, and the “right” one really depends on your health, budget, and how you like to handle medical bills.
Quick Refresher: What Does a Medigap Plan Do?
Original Medicare (Parts A and B) is a great foundation, but it doesn’t pay 100% of your medical costs. You’re still responsible for deductibles, coinsurance, and copayments. A Medigap plan, also called a Medicare Supplement, helps cover many of those “gaps,” so your out-of-pocket costs are more predictable (Medicare.gov).
The good news is that Medigap plans are standardized. That means Plan G from one company in Florida must offer the same medical benefits as Plan G from another company. The big differences are price, service, and how the plan fits your personal situation.
Plan G: The “Peace-of-Mind” Option
Medigap Plan G is often called the most comprehensive plan available to people new to Medicare. After you pay the annual Medicare Part B deductible, Plan G steps in and covers virtually all of your Medicare-approved costs for the year:
- Part A hospital coinsurance and up to 365 extra hospital days
- Part B coinsurance or copayments for doctor visits and outpatient care
- First three pints of blood and hospice coinsurance or copays
- Skilled nursing facility coinsurance and the Part A deductible
- Limited foreign travel emergency coverage (up to plan limits)
The only major thing Plan G does not pay is the Medicare Part B deductible. After that, most Florida beneficiaries on Plan G see very little in medical bills for Medicare-covered services throughout the year (Healthline).
Real-World Florida Example: Plan G
Imagine Carol, a 68-year-old retiree in Port St. Lucie. She has diabetes and sees several specialists each year. She also likes to travel to visit her grandkids out of state. With Plan G, Carol pays her Part B deductible once a year. After that, nearly every Medicare-approved visit, test, or procedure is covered. She loves not worrying about copays every time she goes to the doctor.
Nationally, the average premium for Plan G for a 65-year-old is often in the $150–$166 per month range, though Florida rates can be higher or lower depending on your ZIP code, age, and tobacco use (CompareMedicare.com). That higher premium is essentially trading monthly cost for maximum predictability.
Plan N: Lower Premium, A Little More Cost Sharing
Plan N is designed for people who want strong coverage but are comfortable paying small copays when they use services. In exchange, they usually enjoy a noticeably lower monthly premium than Plan G (Forbes Advisor).
- You still get coverage for hospital coinsurance, Part A deductible, hospice, blood, and skilled nursing facility coinsurance—similar to Plan G.
- You pay up to $20 for some doctor visits and up to $50 for emergency room visits (waived if you’re admitted).
- Plan N does not cover Part B excess charges, though many Florida doctors accept Medicare assignment and do not bill these extra amounts.
Nationally, a 65-year-old might see Plan N around $115–$125 per month on average, with some areas lower and some higher (SmartBenefitUSA). That monthly savings compared to Plan G can add up over the year.
Real-World Florida Example: Plan N
Now picture Joe, a 67-year-old in Vero Beach who’s generally healthy. He sees his primary care doctor a couple of times a year and maybe a specialist once. Joe chooses Plan N because:
- He saves, for example, $30–$40 a month in premiums compared to Plan G.
- He’s fine paying a small copay when he actually goes to the doctor.
Over a year, Joe might pay a few small copays, but his total spending could still be lower than if he’d paid the higher Plan G premium—especially if he barely uses the plan.
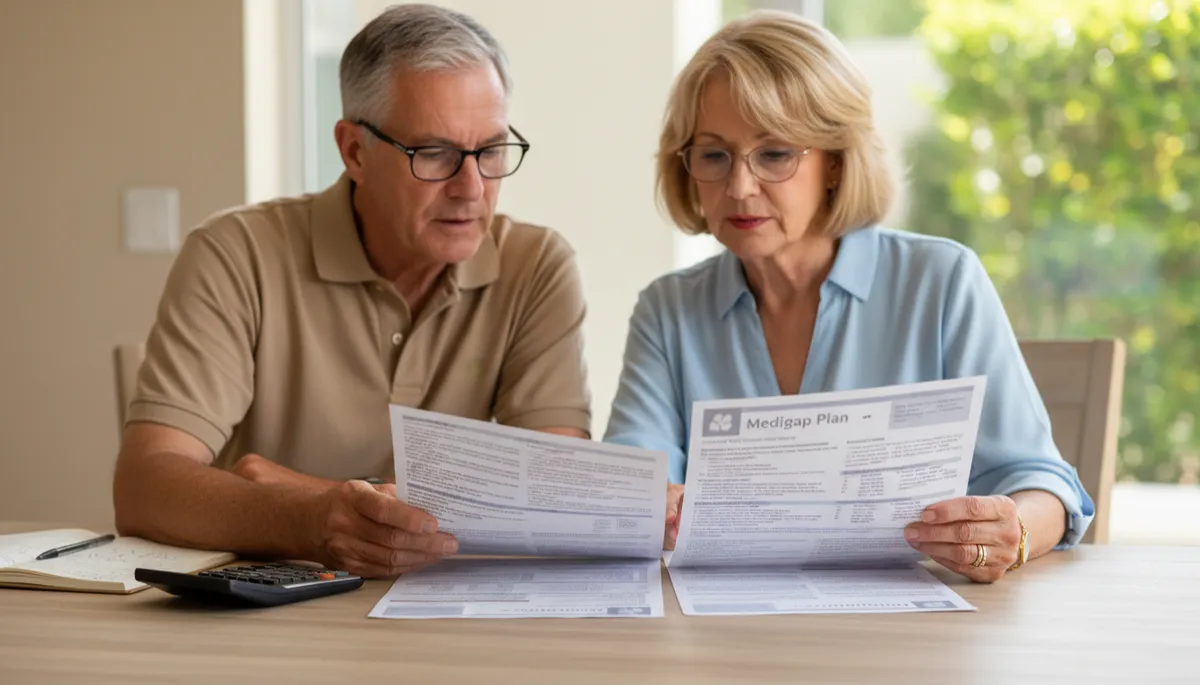
Comparing premiums and copays side by side helps reveal which plan truly fits your budget.
Plan G vs. Plan N: How to Decide What Fits You
When we talk with Florida Medicare beneficiaries at NP Health Solutions, we usually walk through three big questions to help choose between Plan G and Plan N:
- How often do you see doctors or specialists? If you have chronic conditions or frequent appointments, Plan G’s higher premium may be worth the near-zero bills later. If you only go a few times a year, Plan N’s copays may be easy to handle.
- Do you prefer predictable costs? Some people love knowing that, after the Part B deductible, almost everything is covered—this leans toward Plan G. Others are comfortable with “pay as you go” copays to keep premiums lower—this leans toward Plan N.
- What does pricing look like in your Florida ZIP code? Rates can vary widely by county, age, and tobacco use. Two neighbors in Stuart could see different premiums from the same company. Getting personalized quotes is essential.
Why Work with a Local, Independent Agency Like NP Health Solutions?
Medigap plans are standardized, but prices and service are not. As an independent agency serving the Treasure Coast and Florida, NP Health Solutions can:
- Compare multiple top-rated Medigap carriers side by side for your exact ZIP code.
- Explain, in plain language, how Plan G and Plan N would work with your doctors and health history.
- Help you understand rate trends, company reputations, and options if premiums jump in the future.
Ready to See Which Plan Is Best for You?
Whether you’re leaning toward the “all-in” peace of mind of Plan G or the lower premiums and small copays of Plan N, the best choice is the one that fits your health, budget, and comfort level with out-of-pocket costs.
If you’re on the Treasure Coast or anywhere in Florida, NP Health Solutions LLC is here to make this simple. We’ll walk you through Plan G vs. Plan N, show you real quotes from multiple companies, and help you decide with confidence—at no cost to you.
Call NP Health Solutions today or request your free Medigap comparison online. In just a short conversation, you’ll know whether Plan G or Plan N is the better fit for your Medicare needs in Florida—and you can get back to enjoying the sunshine, not stressing over medical bills.


© NP Health Solutions LLC 2026 All Rights Reserved.
Made By